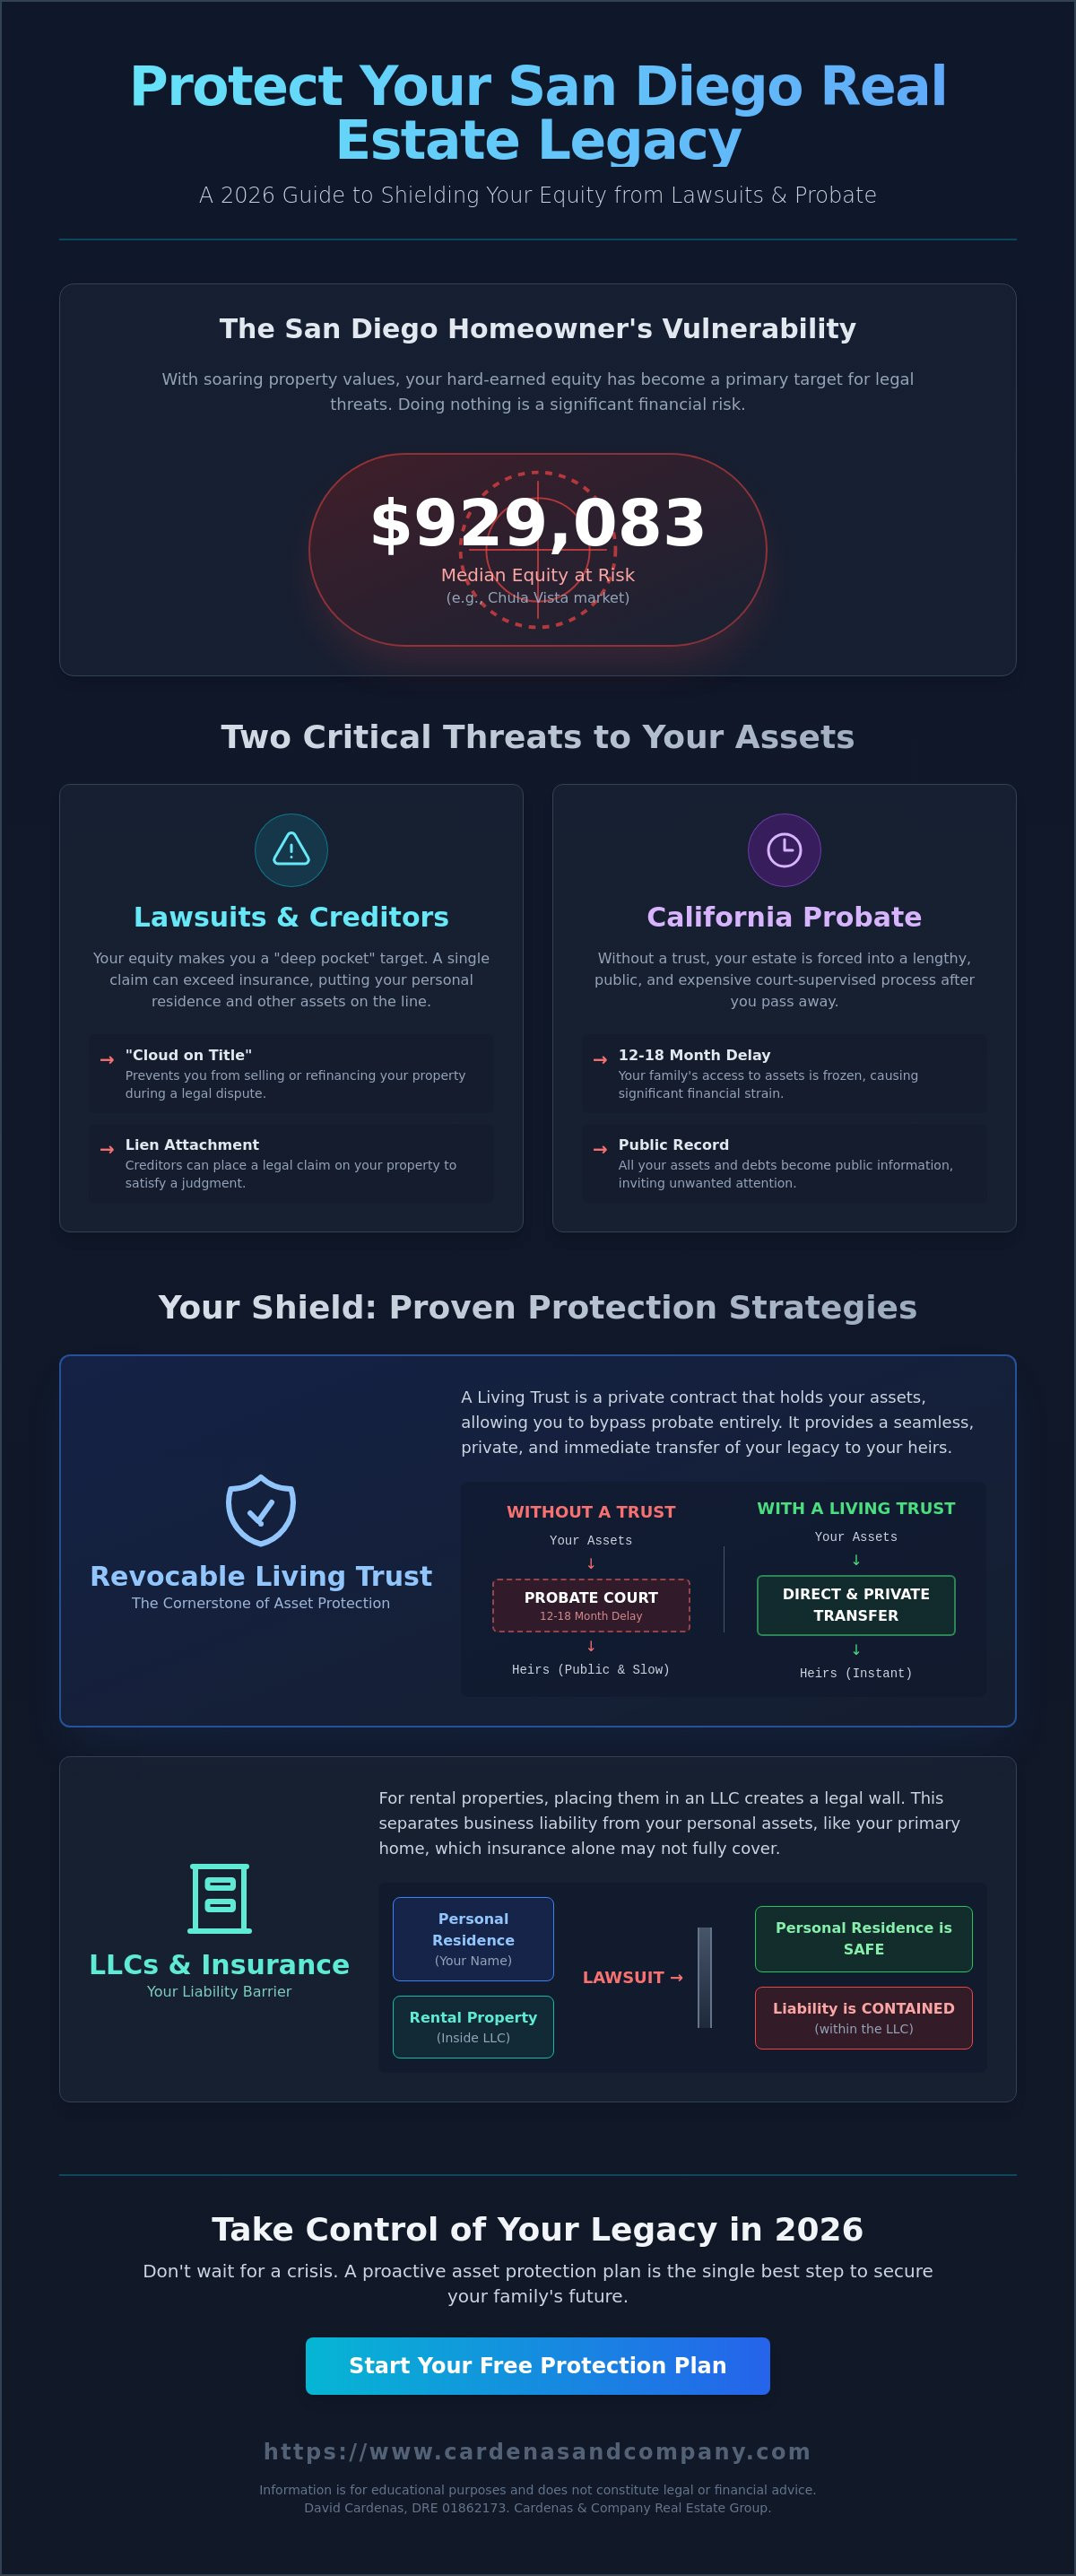
What if a single legal claim against your Chula Vista rental could strip away the $929,083 in median equity you've spent decades building? You've worked hard to secure your piece of the San Diego market, but the fear of a frivolous lawsuit or the notorious 12-18 month California Probate, the court-supervised legal process of settling an estate and distributing assets after someone passes away, keeps many homeowners awake at night. It's frustrating to feel like your wealth is vulnerable to creditors or bureaucratic delays. Implementing a proactive strategy for real estate asset protection San Diego is the only way to ensure your property remains a source of stability rather than a legal liability.
We believe your legacy deserves more than a generic plan that leaves you exposed to Proposition 19 tax hikes or predatory litigation. This guide provides a clear roadmap to insulate your primary residence and rental portfolio using tools like Living Trusts and LLCs. You'll learn how to manage the 2026 Medi-Cal asset limits of $130,000, stay below the $184,500 small estate threshold, and maintain control over your assets. By the end, you'll have the technical clarity and peace of mind needed to protect your family's future in the South Bay and beyond.
Key Takeaways
- Discover how a Revocable Living Trust allows your heirs to avoid Probate, the 12 to 18-month court-supervised asset distribution process, ensuring your family legacy stays private and intact.
- Learn why the Chula Vista Bayfront project and Amara Bay developments have increased the urgency for real estate asset protection San Diego as local property values continue to climb.
- Compare the effectiveness of high-limit umbrella insurance against legal entity structuring to find the right balance of liability coverage for your residential portfolio.
- Identify the first steps to conducting a comprehensive equity inventory so you can make informed decisions about your 2026 wealth strategy.
Table of Contents
Why San Diego Homeowners Need Asset Protection in 2026
Asset protection is a legal framework designed to shield your property from creditors, lawsuits, or judgments. In the current market, where the San Diego median home price reached $929,083 on March 31, 2026, your home is no longer just a shelter; it's a significant financial target. Implementing asset protection strategies ensures that the wealth you've built isn't siphoned away by a single legal dispute. We view this as the foundation of any sound wealth strategy because you can't grow what you can't keep.
Homeowners in established neighborhoods like Del Cerro and Allied Gardens often sit on significant "hidden" equity. If you bought your home a decade ago, your net worth has likely surged, making you a "deep pocket" target for aggressive litigants. We've seen that high-equity positions without a protective barrier are simply accidents waiting to happen. Effective real estate asset protection San Diego shifts your position from vulnerable to fortified by creating legal distance between your personal life and your property holdings.
The Risk of Doing Nothing
Choosing to ignore these risks creates a dangerous exposure to Liability, which is the legal responsibility for one’s acts or omissions. Imagine a tenant or guest suffers a slip-and-fall at your rental property in Chula Vista. Without proper entity structuring, a judgment exceeding your insurance limits could allow a creditor to place a lien on your personal residence. We see this happen when owners rely solely on basic insurance policies that often contain exclusions for specific types of claims, making proactive physical security from San Diego CCTV Pros an essential part of documenting and preventing potential liability incidents.
Equity as a Target
Aggressive creditors and "lawsuit mill" attorneys regularly scan San Diego County public records to identify high-value real estate holdings. They look for properties owned in personal names because those are the easiest to attach to a lawsuit. If a legal claim is filed, it can create a Cloud on Title, which is a claim or encumbrance that makes the ownership of a property questionable. This prevents you from selling or refinancing until the matter is resolved, often forcing a settlement just to regain control of your own asset. Early planning is the only way to prevent these public records from becoming a roadmap for your financial downfall.
Bottom Line: Protecting your San Diego property requires moving beyond simple insurance to a structured legal defense of your equity. Taking action now prevents future legal claims from freezing your assets or draining your family's wealth.
We invite you to a strategy session with David & Angela Cardenas and the Cardenas & Company Real Estate Group to review your holdings. Visit TrustSanDiego.com or cardenasandcompany.com to start securing your legacy today.
The Living Trust: Your Shield Against California Probate
A Revocable Living Trust is the cornerstone of real estate asset protection San Diego. It functions as a private legal contract that dictates exactly how your property is managed while you're alive and how it's distributed after you pass. Without one, your estate falls into Probate, which is the court-supervised process of distributing a deceased person’s assets. In San Diego, this bureaucratic hurdle often drags on for 12 to 18 months, freezing your family's access to equity and forcing them into a public spotlight.
By holding your property in a trust, you ensure an instant transfer of ownership to your heirs. This bypasses the court entirely. It also keeps your financial affairs private, as trust documents aren't filed with the court like a will is. For families looking to secure their future, resources at TrustSanDiego.com provide the specific education needed to get started.
Why Will-Based Plans Often Fail in San Diego
Relying on a simple Will is often the biggest obstacle to effective real estate asset protection San Diego. Many homeowners mistakenly believe a Will protects them. It doesn't. A Will is essentially a letter to a judge that guarantees your estate will enter the California probate process. This is an expensive mistake. California law sets statutory fees for attorneys and executors based on the gross value of the estate, not the net equity.
Consider a typical home in Mira Mesa valued at $1,200,000. Even if the mortgage is high, the probate fees are calculated on that full gross valuation. Statutory fees alone can strip 3-5% of the home’s value, potentially costing your heirs $36,000 to $60,000 just to settle the estate. These costs are often paid out of the home's equity, reducing the inheritance you intended for your children.
Maintaining Control and Flexibility
Setting up a trust doesn't mean losing control. You remain the trustee, meaning you can buy, sell, or refinance your property just as you did before. When you decide to sell, the property moves through Escrow seamlessly. We define Escrow as a neutral third party that holds funds and documents during a real estate transaction to ensure all conditions are met before the sale closes.
The process is virtually identical to a standard sale, but the trust provides a layer of continuity that a personal deed cannot. If you're curious about how this fits into your broader portfolio, reviewing your current equity position with a strategist is a vital first step.
Bottom Line: A Revocable Living Trust is the most effective way to shield your San Diego home from the delays and costs of probate. It ensures your equity transfers privately and instantly to your loved ones without court interference.
We invite you to a strategy session with David & Angela Cardenas and the Cardenas & Company Real Estate Group to review your holdings. Visit TrustSanDiego.com or cardenasandcompany.com to start securing your legacy today.
Liability Protection: Insurance vs. Entity Structuring
We view liability protection as a three-pillar system: insurance, equity stripping, and legal entities. While a Living Trust manages the transfer of your assets, it doesn't provide a shield against personal liability for accidents occurring on your property. For that, you need a robust strategy for real estate asset protection San Diego that builds both financial and legal barriers. As you work through your Amortization, the process of paying off a debt over time through regular installments, your growing equity becomes an increasingly attractive target for litigants.
Relying solely on a basic homeowner's policy is a common mistake that leaves your personal wealth exposed. High-limit umbrella insurance and legal entities like LLCs serve different but complementary roles. One provides the cash to settle a claim, while the other prevents a creditor from reaching your personal bank accounts or primary residence if a judgment exceeds your policy limits.
The LLC Strategy for Rental Properties
Investors with rental holdings in Santee or Serra Mesa should consider the "Corporate Veil" provided by a Limited Liability Company. This legal separation ensures that if a tenant or visitor is injured on the property, their claim is generally limited to the assets held within that specific LLC. For those looking to diversify their portfolio and buy RCFE facility California, we advocate for a "one property, one LLC" philosophy for high-value San Diego assets to prevent a single incident from jeopardizing your entire portfolio.
Transparency is key here; maintaining an LLC in California isn't free. You must account for the $800 annual Franchise Tax Board fee and the administrative work required to keep the entity in good standing. If you fail to follow these formalities, a court could "pierce the veil," allowing creditors to bypass the LLC and target your personal assets. We recommend reviewing your portfolio structure annually to ensure your protections remain intact as market values rise.
Umbrella Insurance: The First Barrier
A high-limit umbrella policy is the most cost-effective first step for any homeowner. These policies typically provide $1,000,000 to $5,000,000 in additional liability coverage that sits on top of your existing auto and home insurance. It's the "first money" out the door in a lawsuit, often settling claims before they ever reach a courtroom. When reviewing your policy, look for these common gaps:
- Exclusions for short-term rental activity (Airbnb/VRBO).
- Restrictions on specific dog breeds or "dangerous" animals.
- Limitations on coverage for libel or slander claims.
- Requirements for specific underlying limits on your base policies.
Bottom Line: Insurance provides the immediate financial defense for your properties, while entity structuring offers the permanent legal separation needed to protect your personal wealth. Combining these tools ensures that a single accident won't derail the legacy you've worked decades to build.
We invite you to a strategy session with David & Angela Cardenas and the Cardenas & Company Real Estate Group to review your holdings. Visit TrustSanDiego.com or cardenasandcompany.com to start securing your legacy today.
Local Insights: Protecting Wealth in Chula Vista and the South Bay
The South Bay is undergoing a massive economic transformation. The Chula Vista Bayfront project is a multi-billion dollar development that has fundamentally shifted the wealth profile of the region. As new luxury developments like Amara Bay come online, homeowners in zip codes like 91910 and 91911 are seeing unprecedented equity growth. This surge in value makes real estate asset protection San Diego a necessity for families who previously didn't consider themselves "wealthy."
In February 2026, the median single-family home price in Chula Vista (91911) reached approximately $810,000. This rapid appreciation is a double-edged sword. While your net worth has increased, so has your exposure to property tax reassessments and legal claims. You can see the impact of this growth firsthand by reviewing the rising values at Chula Vista Bayfront Condos, where the market continues to set new benchmarks for the area.
Prop 19 and Inherited Real Estate
Long-term owners in Chula Vista face a significant threat from Proposition 19. This law mandates that inherited property not used as a primary residence within one year must be reassessed at current market value. For a family home purchased decades ago, this can result in a property tax bill that increases by thousands of dollars overnight. We use various strategies to mitigate these hikes, which often hinge on interest rate movements measured in Basis Points. We define Basis Points as a unit of measure for interest rates and other percentages in finance, where one basis point equals 1/100th of 1%.
The Military Family Perspective
San Diego's high population of service members requires a specialized approach to asset protection. Many military families utilize VA loans to purchase homes in Otay Ranch or Eastlake before relocating out of the area. When you transition your primary residence into a rental property, your liability profile changes instantly. Protecting these assets while you are stationed elsewhere is critical to maintaining your financial stability. For a deeper look at these specific challenges, we recommend our Comprehensive Guide to Military Relocation.
If you own property in the South Bay, you need a strategy that accounts for both your rising equity and the unique tax laws of California. You can schedule a portfolio review with us to ensure your protection plan matches your current market valuation.
Bottom Line: The equity boom in Chula Vista driven by the Bayfront development requires a proactive defense against tax reassessments and liability. Military and long-term families must update their legal structures to reflect the new wealth profile of the South Bay.
We invite you to a strategy session with David & Angela Cardenas and the Cardenas & Company Real Estate Group to review your holdings. Visit TrustSanDiego.com or cardenasandcompany.com to start securing your legacy today.
Designing Your 2026 San Diego Asset Protection Plan
Executing a successful strategy for real estate asset protection San Diego requires more than just signing a few documents. It is a deliberate, multi-step process that aligns your legal structures with your financial goals. To keep your physical estate plans and legal files organized, Custom Binding Products offers local binding and laminating supplies to ensure your records are both professional and durable. If you haven't audited your holdings recently, your plan likely lacks the technical rigor required for the 2026 market.
- Step 1: Conduct a full inventory. Document every piece of real estate equity and all liquid assets. You cannot protect what you haven't quantified.
- Step 2: Verify market valuations. Consult with a wealth-focused real estate broker to get an accurate valuation of your portfolio. On March 31, 2026, the San Diego median home price hit $929,083, but hyper-local shifts in the South Bay may have changed your specific equity position.
- Step 3: Draft or update your Living Trust. Coordinate with legal counsel to ensure your properties are titled correctly to avoid Probate. We define Probate as the court-supervised legal process of settling an estate and distributing assets after someone passes away.
- Step 4: Align your insurance. Review your umbrella and landlord policies to ensure they match your current equity levels. If your property value has increased by the forecasted 2% to 4% this year, your old coverage limits are likely insufficient.
The Collaborative Approach
We believe that your real estate agent, CPA, and attorney must work in sync to build a truly impenetrable legacy. If your attorney creates a trust but your broker doesn't understand how to handle the deed during Escrow, the entire system breaks down. We define Escrow as a neutral third party that holds funds and documents during a real estate transaction to ensure all conditions are met. We invite you to join us for a strategy session at cardenasandcompany.com to see how a unified team can simplify these complex requirements.
Quarterly Reviews and Maintenance
Asset protection is not a task you "set and forget." Market shifts in San Diego County home prices and changing California tax regulations mean your plan must remain fluid. A plan that worked in 2024 may leave you vulnerable to Proposition 19 reassessments or new liability claims in 2026. Regular maintenance is the only way to secure the legacy you worked decades to build and ensure your family's long-term stability.
Bottom Line: A well-designed protection plan requires a coordinated effort between your legal, tax, and real estate advisors. Regular audits of your equity and insurance coverage are essential to maintaining a defensive shield around your San Diego property holdings.
We invite you to a strategy session with David & Angela Cardenas and the Cardenas & Company Real Estate Group to review your holdings. Visit TrustSanDiego.com or cardenasandcompany.com to start securing your legacy today.
Securing Your San Diego Legacy for the Next Generation
Your equity in neighborhoods like Otay Ranch and Allied Gardens represents a lifetime of discipline. Safeguarding this wealth through real estate asset protection San Diego ensures that market shifts or legal challenges don't compromise your family's future. By integrating a Living Trust to avoid Probate, the court-supervised process of distributing assets, and utilizing entity structuring to shield your rentals, you transition from a passive owner to a proactive wealth strategist. These steps are the most effective way to insulate your holdings from the 12 to 18-month delays typical in California courts.
We've spent over 25 years helping San Diego and South Bay families build relationship-driven wealth strategies. Whether you're a military family managing a relocation or a long-term owner facing Proposition 19 tax reassessments, your situation requires specialized attention. We invite you to schedule your real estate wealth strategy session to review your unique portfolio. Taking action now provides the certainty your family deserves.
Bottom Line: Protecting your real estate equity is the most critical step in ensuring your hard work translates into a lasting family legacy. A proactive plan today prevents the high costs of legal disputes and court-supervised probate tomorrow.
We invite you to a strategy session with David & Angela Cardenas and the Cardenas & Company Real Estate Group to review your holdings. Visit cardenasandcompany.com or TrustSanDiego.com to start securing your legacy today.
Frequently Asked Questions
Is a living trust the same as asset protection in San Diego?
No, a living trust is not the same as a comprehensive strategy for real estate asset protection San Diego. A trust's primary job is to avoid Probate, the court-supervised legal process of settling an estate after someone passes away. While it manages the transfer of wealth, it doesn't shield your property from a personal lawsuit or creditor claim while you're alive. True protection requires layering trusts with insurance and legal entities like LLCs.
Do I need an LLC if I only own one rental property in Chula Vista?
An LLC is highly recommended even for a single rental in Chula Vista because it separates your business risks from your personal residence. Without this separation, a slip-and-fall at your rental could allow a litigant to target your personal bank accounts. You must weigh this benefit against the $800 annual California Franchise Tax Board fee. We find that most owners prefer the certainty of knowing their primary home is safe.
How much does it cost to set up an asset protection plan in California?
The cost varies based on the complexity of your real estate holdings and the number of entities required to shield them. A basic plan for a primary residence is less involved than a strategy for a multi-property portfolio with out-of-state assets. We focus on a value-based approach where the cost of the plan is a fraction of the equity we're helping you preserve. Investing in a professional structure now prevents the much higher costs of a 12-month probate or a legal judgment.
Can I put my primary San Diego residence into an LLC?
While possible, placing your primary residence into an LLC is rarely a good idea. Doing so can trigger a "due-on-sale" clause in your mortgage and might disqualify you from the $250,000 or $500,000 capital gains tax exclusion when you sell. Most homeowners use a Revocable Living Trust for their primary home and save LLCs for their rental properties. This provides the right balance of tax benefits and probate avoidance.
What happens to my San Diego property if I die without a trust?
If your property value exceeds $184,500, it must go through the formal Probate process. This is a public and expensive court procedure that currently takes 12 to 18 months in San Diego County. Your family won't be able to sell or refinance the home without court approval. This delay often creates a financial crisis for heirs who need access to equity to pay for funeral costs or property taxes.
Will asset protection help me save on property taxes?
Standard real estate asset protection San Diego structures don't directly lower your annual tax bill. However, they are essential for managing Proposition 19 consequences, which can cause a massive tax reassessment when property passes to children. By planning ahead, you can often mitigate these hikes and keep the original tax basis for your heirs. This is a critical consideration for long-term owners in high-growth areas like San Diego and the South Bay.
How does an umbrella policy work with my existing home insurance?
An umbrella policy provides an extra layer of liability coverage that sits on top of your primary home and auto insurance limits. If you're sued for $2,000,000 but your home policy only covers $500,000, the umbrella policy pays the remaining balance. It's one of the most cost-effective ways to protect your net worth from catastrophic claims. It acts as the first line of defense before a creditor can even look at your property equity.
Can a creditor take my home if it is in a living trust?
Yes, a creditor can generally reach assets held in a revocable living trust. Because you maintain full control over the trust and can move assets in and out at will, the law doesn't treat the trust as a separate entity for liability. To get true creditor protection, you must use more advanced tools like irrevocable trusts or LLCs. We help you determine which level of defense is appropriate for your specific risk profile.
Bottom Line: Implementing a proactive asset protection plan is the only way to ensure your San Diego equity isn't drained by legal fees or court delays. A combination of insurance, trusts, and entities provides the stability your family legacy requires.
We invite you to a strategy session with David & Angela Cardenas and the Cardenas & Company Real Estate Group to review your holdings. Visit cardenasandcompany.com or TrustSanDiego.com to start securing your legacy today.
Disclaimer
The information provided on this blog is for educational and informational purposes only and does not constitute legal, financial, or investment advice. While we strive for accuracy, real estate markets and insurance regulations (including Living Trusts and IUL strategies) are subject to change. David Cardenas (DRE 01862173) is a licensed real estate salesperson; however, this content does not create an agency relationship. Please consult with a qualified attorney or tax professional regarding your specific situation.