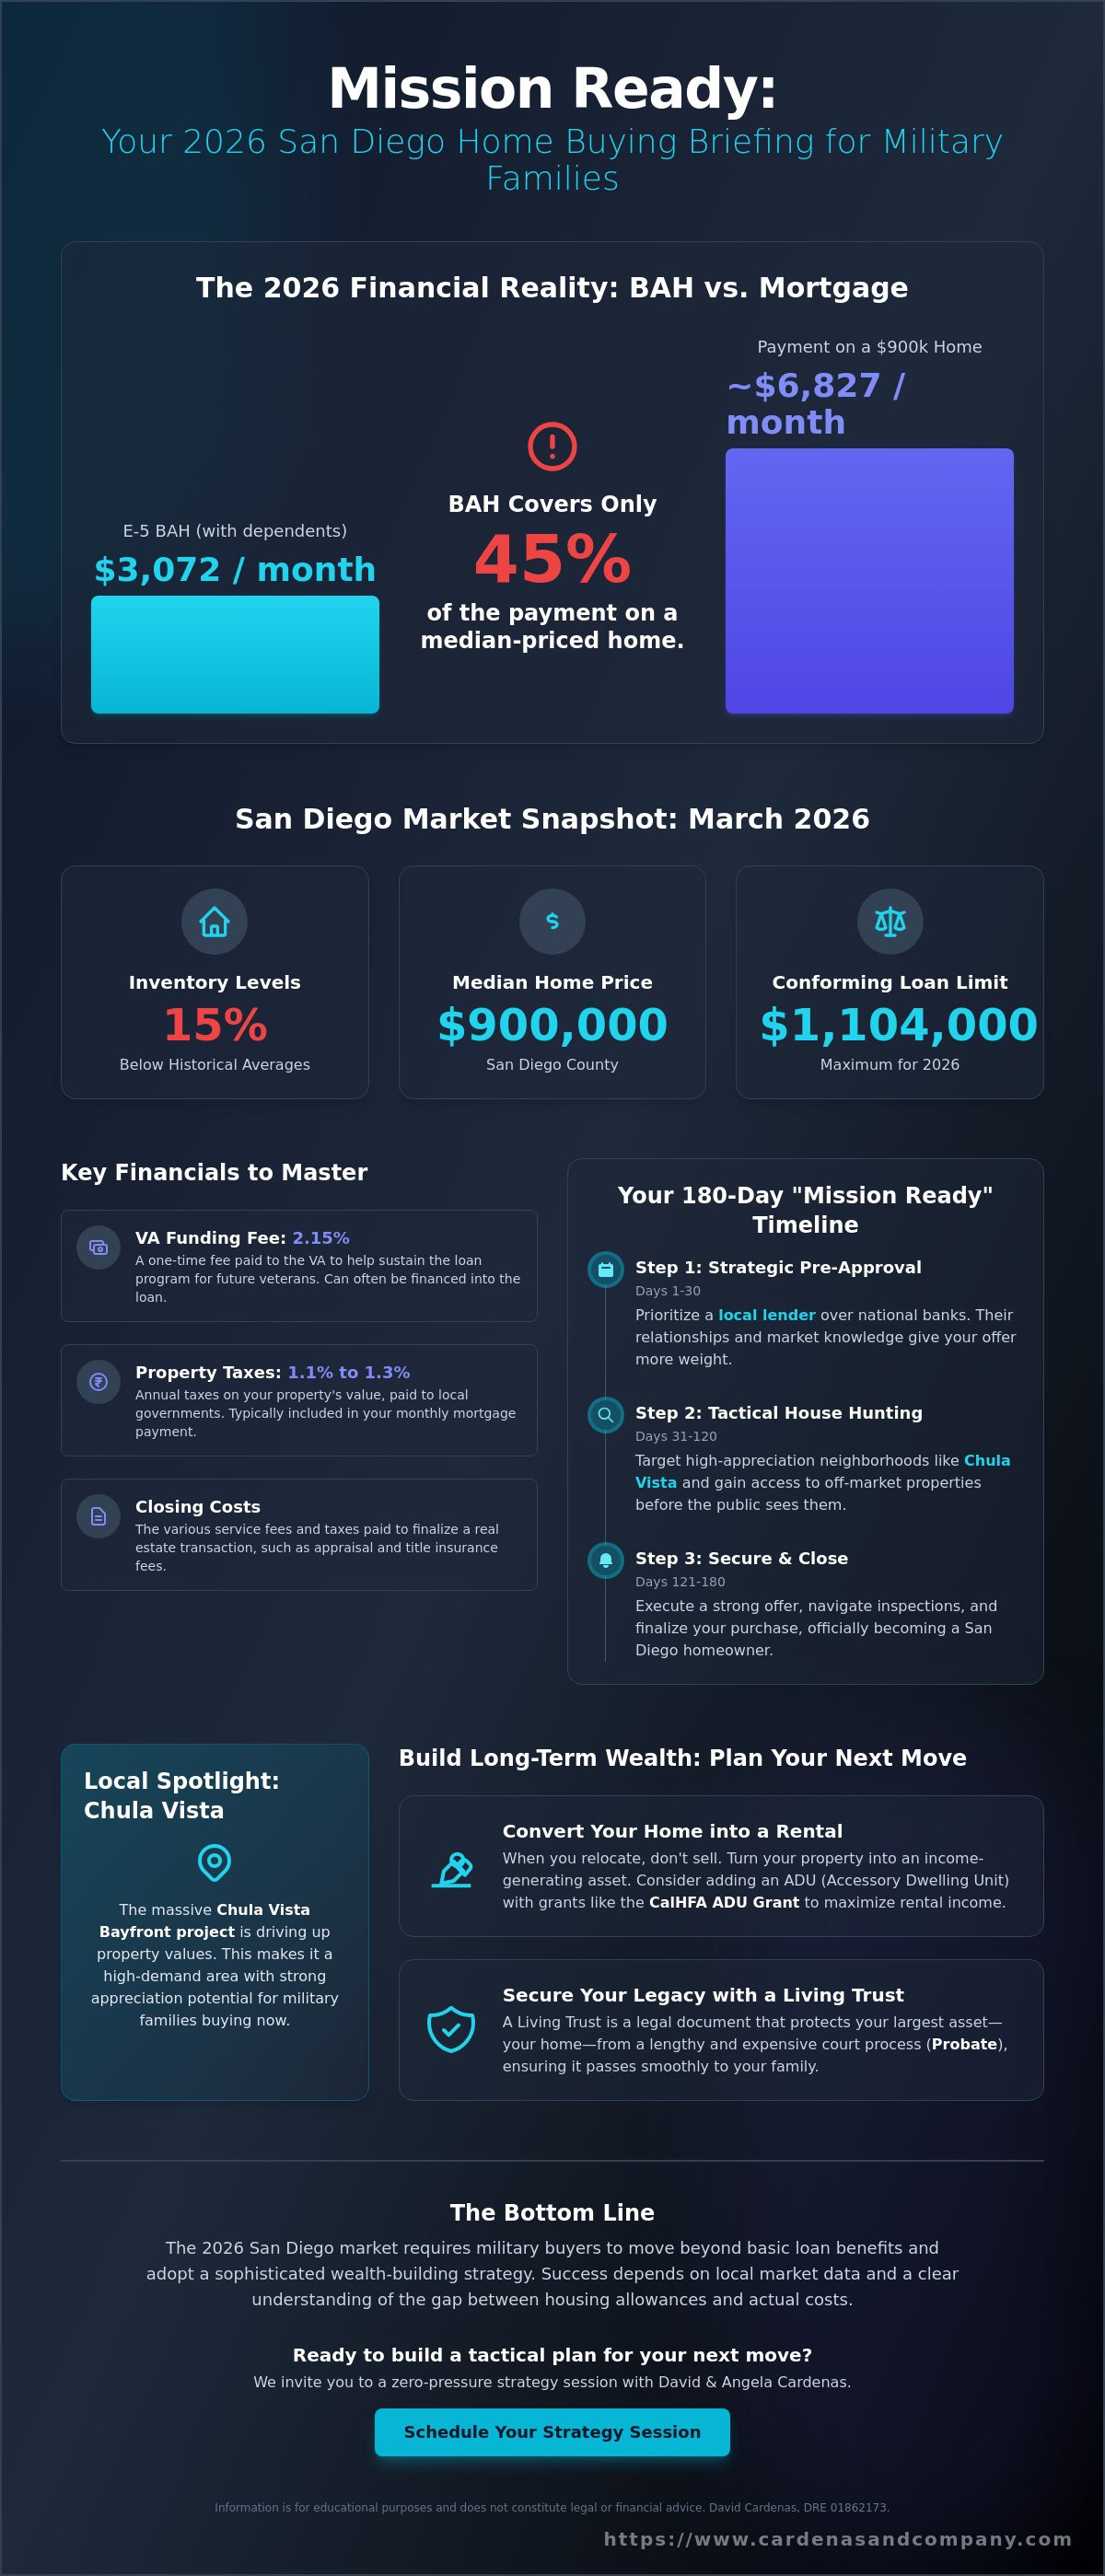
In 2026, the BAH for an E-5 with dependents in San Diego is $3,072, yet this covers only 45% of the monthly payment on a $900,000 median-priced home. It's a sobering statistic for families stationed at 32nd St, Miramar, or North Island who are tired of losing wealth to rising rents. We understand that finding military home buying programs San Diego families can actually use is difficult when inventory is low and the gap between housing costs and allowances continues to widen.
We promise to show you exactly how to bridge this financial gap by layering federal benefits with local wealth-building strategies. You'll learn how to manage closing costs, which are the service fees and taxes paid at the end of a real estate transaction, while handling the 2.15% VA funding fee. We'll also explain how amortization, the schedule of paying off your loan principal and interest over time, works in your favor when you're building equity in Chula Vista.
This guide breaks down the $1,104,000 conforming loan limit for 2026 and identifies specific local grants that help military buyers compete. We'll look at how upcoming developments like the Chula Vista Bayfront project impact local values. We're moving past the fluff to give you a tactical plan for securing a home and ensuring your family's long-term stability in the San Diego market.
Key Takeaways
- Understand why inventory levels remain 15% below historical averages in March 2026 and how to target specific neighborhoods like Chula Vista effectively.
- Discover how to layer federal benefits with specialized military home buying programs San Diego offers, such as the CalHFA ADU Grant for generating rental income.
- Perform the "Rent vs. Buy" math for the South Bay to determine exactly when homeownership becomes more profitable than using BAH for rent.
- Execute a 180-day strategic timeline that prioritizes local pre-approval over national banks to increase your offer's strength in a competitive market.
- Plan for your next relocation by learning to convert your home into a rental property and securing your legacy with a Living Trust, a legal document that protects your assets from the court system.
Table of Contents
Strategic Realities of the 2026 San Diego Military Housing Market
The San Diego housing market doesn't wait for anyone, especially in March 2026. Inventory levels are currently 15% below historical averages. This scarcity means you're competing against cash buyers and institutional investors for limited single-family homes in Chula Vista and Serra Mesa. A successful purchase requires a tactical "Mission Ready" mindset that prioritizes data over emotion. While many look for military home buying programs San Diego offers, the real challenge is finding a property that fits your budget before it disappears.
Transparency is vital here. In 2026, the BAH for an E-5 with dependents is $3,072, but the median home price in San Diego County has reached $900,000. This creates a significant gap between your allowance and the actual mortgage payment. You must be prepared to use secondary income or significant savings to make the math work. Relying solely on your housing allowance to cover a South Bay mortgage is no longer a realistic strategy for most service members.
Inventory and Competition Near San Diego Bases
Availability in the South Bay remains incredibly tight for those stationed at Naval Base San Diego. The ongoing Chula Vista Bayfront project is actively driving up local property values as new infrastructure and amenities come online. This development makes Chula Vista a high-demand area for both residents and investors. To succeed, you need access to "off-market" opportunities. These are homes for sale that aren't yet listed on major public websites, giving you a head start before the general public sees them.
Defining the 2026 Financial Landscape
Interest rates are often discussed in terms of Basis Points. These are units of measure for interest rates, where 100 points equal 1%. In the current market, a shift of just 50 Basis Points can drastically alter your monthly purchasing power. The VA Loan Program remains a foundational tool, but it's only one part of your strategy. We're seeing many families adopt a "Buy Now, Refinance Later" approach. They secure the home today at a higher rate and plan to adjust the loan when rates drop, though this requires enough monthly cash flow to sustain the initial payment.
To stay competitive, your strategy should include:
- Targeting homes in San Diego and Chula Vista with high appreciation potential.
- Accounting for property taxes, which typically range from 1.1% to 1.3% in this region.
- Preparing for closing costs, the administrative and legal fees paid at the end of the transaction.
Bottom Line: The 2026 San Diego market requires military buyers to move beyond basic loan benefits and adopt a sophisticated wealth-building strategy. Success depends on local market data and a clear understanding of the gap between housing allowances and actual costs.
Ready to build a tactical plan for your next move? We invite you to a zero-pressure strategy session with David & Angela Cardenas and the Cardenas & Company Real Estate Group at cardenasandcompany.com or TrustSanDiego.com.
Information is for educational purposes and does not constitute legal or financial advice. David Cardenas, DRE 01862173.
Beyond the VA Loan: Local Home Buying Programs for Service Members
The VA Loan Program is the gold standard for military buyers, but it doesn't always bridge the gap in a market where median prices hit $900,000. You need to look at military home buying programs San Diego offers at the state and county level to gain a competitive edge. Layering these local grants on top of your VA entitlement can significantly reduce your out-of-pocket closing costs, which are the various fees and expenses paid at the end of a real estate transaction. We've seen families successfully enter the market with nearly zero out-of-pocket expenses by combining these resources strategically.
One of the most powerful tools in 2026 is the CalHFA ADU Grant Program. This provides up to $40,000 for the construction of an Accessory Dwelling Unit. For a military family, this isn't just about extra space; it's about creating a rental income stream that helps cover your mortgage when you eventually PCS out of the area. Additionally, the San Diego County First-Time Homebuyer Down Payment Assistance Program (DPA) offers low-interest, deferred-payment loans that can be used for a down payment or to cover closing costs, though eligibility depends on specific income limits and the location of the property.
Don't overlook the California Disabled Veterans’ Property Tax Exemption. If you have a service-connected disability, you may qualify for a significant reduction in the assessed value of your home. This directly lowers your monthly property taxes, making high-value areas like Chula Vista more accessible. For a broader look at your options, the Naval Base San Diego Housing Resources provide essential counseling and database access for off-base housing.
State-Level Support: CalHFA for Veterans
The California Dream For All shared appreciation loan is a unique option for 2026. This program provides a down payment in exchange for a portion of your home's future value increase. In high-growth sectors like Otay Ranch, giving up a percentage of your equity is a steep price for entry. We often help clients weigh these financial strategies to see if the immediate benefit of a lower monthly payment outweighs the long-term cost of shared equity.
Local San Diego and Chula Vista Incentives
In Chula Vista, specific closing cost assistance programs exist to help residents stay in the community. Our team also tracks specific builder incentives that aren't always publicized. Many developers in the South Bay offer credits toward closing costs specifically for military members to help fill new developments. During the buying process, you'll enter Escrow, which is a neutral third party holding funds during the transaction to ensure both the buyer and seller meet their obligations. This process protects your earnest money while you conduct inspections and finalize your military home buying programs San Diego applications.
Bottom Line: Layering local grants with federal benefits is the most effective way to manage the high cost of entry in the San Diego market. Understanding the trade-offs between immediate assistance and long-term equity is vital for your financial health.
Ready to explore which programs fit your specific situation? We invite you to a zero-pressure strategy session with David & Angela Cardenas and the Cardenas & Company Real Estate Group at cardenasandcompany.com or TrustSanDiego.com.
Information is for educational purposes and does not constitute legal or financial advice. David Cardenas, DRE 01862173.
Analyzing San Diego BAH vs. Homeownership Costs
In 2026, an E-5 with dependents receives approximately $3,072 in BAH. While an O-5 receives significantly more, the gap remains wide when facing a $900,000 median home price. Renting might feel safer, but it offers zero return on investment. Buying a home allows you to use your BAH for Amortization, which is the process of paying off debt over time through regular payments. This shifts your monthly allowance from an expense to a wealth-building contribution that eventually results in full ownership.
Transparency is essential when calculating your budget in this landscape. We often see families struggle because they only look at the mortgage payment and ignore the total cost of carry, which includes finding reliable coverage through providers like SI Insurance. Using military home buying programs San Diego families rely on can help bridge the gap, but the math must be precise. You're not just buying a home; you're acquiring an asset that requires a clear understanding of your monthly cash flow.
The South Bay Advantage
Chula Vista continues to be a strategic choice for military families. When you compare the price-per-square-foot in Rancho San Diego to Mira Mesa, the value in the south becomes clear. You get more house for your dollar while staying close to the bases. Check our South Bay San Diego Homes for Sale Guide to see how current inventory levels in these neighborhoods compare.
Property Taxes and Mello-Roos
You must account for more than just the principal and interest. Property taxes in San Diego typically range from 1.1% to 1.3%, but many newer developments in Eastlake and Otay Ranch include Mello-Roos. This is a special tax assessment used to fund local infrastructure like schools and roads. To find the right fit, we look at your total PITI, which stands for Principal, Interest, Taxes, and Insurance. Utilizing resources such as San Diego County Veteran Homebuyer Programs can help you identify neighborhoods where your total payment remains manageable.
Bottom Line: Your BAH is most effective when used to build long-term equity rather than paying a landlord's mortgage. Successful ownership in San Diego requires a precise calculation of total monthly costs, including taxes and special assessments.
Ready to see the math for your specific rank and target neighborhood? We invite you to a zero-pressure strategy session with David & Angela Cardenas and the Cardenas & Company Real Estate Group at cardenasandcompany.com or TrustSanDiego.com.
Information is for educational purposes and does not constitute legal or financial advice. David Cardenas, DRE 01862173.
Mission Readiness: A Strategic Buying Timeline
Buying a home in San Diego requires a timeline as precise as a military operation. You should start your research 180 days before your report date to understand inventory levels and identify the best military home buying programs San Diego has available. Early action allows you to monitor market shifts and secure a property before the peak summer PCS surge hits the South Bay and Chula Vista markets. Waiting until you arrive often leads to rushed decisions and missed opportunities for wealth building.
Tactical pre-approval is your next critical step. A local San Diego lender is your greatest asset because they carry a reputation that national "big box" banks simply don't have. Sellers in San Diego want to know that your lender understands local property taxes and can close the transaction on time. We've seen many VA offers rejected simply because the listing agent didn't trust a national lender's ability to navigate California's specific closing requirements.
The 180-Day PCS Strategy
Starting six months out gives you the luxury of patience. We utilize high-definition video tours and local advocacy to help families buy remotely, ensuring their home is ready the day they drive into town. This approach eliminates the need for expensive temporary housing or "throwing away" BAH on a short-term rental. To see how we manage these moves, read our Comprehensive Military Relocation Guide.
Winning in a Seller’s Market
In a competitive landscape, your offer must be "clean." This means having a solid pre-approval, minimal contingencies, and a clear timeline. We leverage our 25 years of local experience to position your VA offer as the most reliable choice for the seller. Sometimes, this involves looking at Probate sales. Probate is the legal process of distributing a deceased person's assets through the court system. These sales can be complex and take longer to close, but they often present opportunities to secure a home in established neighborhoods like Serra Mesa without the typical bidding war.
Bottom Line: A successful 2026 purchase depends on starting your search six months early and using a local lender to strengthen your offer. Precision in your timeline and neighborhood selection ensures your home remains a stable financial asset for years to come.
Ready to start your 180-day countdown with a team of experts? We invite you to a zero-pressure strategy session with David & Angela Cardenas and the Cardenas & Company Real Estate Group at cardenasandcompany.com or TrustSanDiego.com.
Information is for educational purposes and does not constitute legal or financial advice. David Cardenas, DRE 01862173.
Building Long-Term Wealth Through Military Homeownership
Homeownership is the first step toward financial independence for military families stationed in San Diego. Once you've secured a property using the military home buying programs San Diego offers, such as the Lead the Way Home Savings Program, your focus must shift from acquisition to preservation. We help you view your home not just as a residence, but as the cornerstone of a multi-generational wealth strategy. Success in the 2026 market requires a proactive approach to managing your equity and protecting your assets from unnecessary legal costs.
When orders take you away from San Diego, you face a critical choice: sell or hold. In neighborhoods like Serra Mesa or Allied Gardens, the demand for single-family rentals remains high. Converting your primary residence into a rental property allows you to keep building equity while a tenant pays down your mortgage. This strategy transforms your BAH-funded asset into a source of passive income that can support your lifestyle long after your service ends.
The "Buy and Hold" Military Strategy
Calculating potential rental income requires a realistic look at the local market and your monthly carrying costs. If you move out of state, you must decide between professional property management or self-management. Professional managers typically charge a percentage of the monthly rent, but they alleviate the stress of repairs and tenant screenings. Visit TrustSanDiego.com to learn about protecting your home as it transitions from a residence to an investment.
Protecting Your Equity
Every San Diego homeowner needs a Living Trust. This is a legal arrangement that allows you to manage your assets while you are alive and ensures they transfer to your heirs without court interference. Without a trust, your estate may be forced into Probate. Probate is the public, court-supervised process of settling a deceased person's debts and distributing their property, which can cost your family thousands in legal fees and take over a year to resolve in California.
We provide regular equity reviews to ensure your home continues to serve your broader financial goals. Whether you plan to use your San Diego equity to fund a child's education or to purchase your next investment property, we act as your long-term wealth mentor. Our goal is to ensure your transition into the next phase of life is backed by a stable, protected financial foundation.
Bottom Line: Building wealth through real estate requires a transition from being a homebuyer to becoming a strategic asset manager. Protecting that wealth with a Living Trust ensures your hard-earned equity remains with your family rather than being lost to the Probate courts.
Ready to discuss your long-term wealth strategy and protect your San Diego assets? We invite you to a zero-pressure strategy session with David & Angela Cardenas and the Cardenas & Company Real Estate Group at cardenasandcompany.com or TrustSanDiego.com.
Information is for educational purposes and does not constitute legal or financial advice. David Cardenas, DRE 01862173.
Secure Your Financial Future in the South Bay
Success in the 2026 market requires moving beyond a standard loan application. By identifying specific military home buying programs San Diego offers and layering them with state grants, you can overcome tight inventory levels and high closing costs. We've seen that a 180-day lead time is the most effective way to ensure your family's transition is stable and wealth-focused. Our team brings 25+ years of local experience as Specialized Military Relocation Professionals (MRP) to ensure you don't just find a house, but secure a lasting financial asset.
We prioritize your long-term stability through meticulous planning and asset protection. You have the tools to build a significant legacy in Chula Vista or San Diego while serving your country. It's about making your BAH work for your family's future rather than a landlord's bottom line. We're here to provide the grounded, expert guidance you need to make this mission a success.
Part of building that legacy includes investing in the moments that matter most. For those looking to celebrate life's milestones with timeless quality, you can explore Laboratory-Grown Diamonds at Brilliant Diamonds Fine Jewelers, a trusted local source for custom jewelry in San Diego.
Bottom Line: San Diego military home buying in 2026 is a tactical operation that requires local expertise and a wealth-driven strategy. You deserve a partner who understands how to layer complex benefits to secure your family's long-term stability.
We invite you to a zero-pressure strategy session with David & Angela Cardenas and the Cardenas & Company Real Estate Group to map out your mission. Visit cardenasandcompany.com or TrustSanDiego.com to get started.
Information is for educational purposes and does not constitute legal or financial advice. David Cardenas, DRE 01862173.
Frequently Asked Questions
What are the best military home buying programs in San Diego for 2026?
The most effective military home buying programs San Diego families use include the VA Loan Program, the CalHFA ADU Grant, and the San Diego County First-Time Homebuyer Down Payment Assistance Program. These tools allow you to combine zero-down financing with grants of up to $40,000 for property improvements. We specialize in layering these benefits to help you compete in high-demand neighborhoods like Chula Vista.
Can I use a VA loan to buy a multi-unit property in Chula Vista?
You can purchase a multi-unit property with up to four units using a VA loan, provided you occupy one of the units as your primary residence. This strategy leverages Amortization, which is the process of paying off debt over time through regular payments, by using tenant rent to cover a portion of your mortgage. It's a proven method for building long-term wealth in the South Bay real estate market.
How does San Diego BAH compare to average mortgage payments in 2026?
In 2026, the BAH for an E-5 with dependents is $3,072, which covers approximately 45% of the monthly payment on a $900,000 median-priced home. This gap represents a significant challenge that requires radical transparency in your financial planning. Most successful military buyers in San Diego utilize a second income or strategic military home buying programs San Diego offers to bridge this difference.
Are there down payment assistance programs for veterans in California?
California provides several options, such as the California Dream For All shared appreciation loan and specific county-level grants. These programs help manage closing costs, the administrative and legal fees paid at the end of the real estate transaction. We help you navigate these state-level benefits to ensure you keep more of your savings during the move.
What is the California Disabled Veterans Property Tax Exemption?
This program offers a substantial reduction in property taxes by lowering the assessed value of a home owned by a veteran with a service-connected disability. It's a vital benefit for those looking at homes in Eastlake or Otay Ranch, where tax rates can be higher due to local bonds. You must file the appropriate paperwork with the San Diego County Assessor to lock in these savings.
How long does it take to close on a home with a VA loan in San Diego?
The typical timeline to close a VA loan in San Diego is 30 to 45 days. This window includes Escrow, which is a neutral third party holding funds during the transaction, and the time required for a VA-certified appraisal. Working with a local lender who understands the San Diego market can prevent delays and keep your "Mission Ready" timeline on track.
Is it better to live in Chula Vista or closer to the San Diego Naval Base?
Living in Chula Vista often provides more square footage and access to newer infrastructure like the Chula Vista Bayfront project, though it results in a longer commute. Staying closer to 32nd St or North Island offers convenience but often means dealing with older inventory levels and higher price-per-square-foot. We help you weigh these lifestyle choices against your long-term equity goals.
What are the current inventory levels for homes near Miramar and North Island?
As of March 2026, inventory levels near Miramar and North Island remain 15% below historical averages. This tight market creates intense competition for single-family homes in Serra Mesa and Allied Gardens. Success in these areas requires a proactive approach and access to off-market properties before they reach the general public.
Bottom Line: Navigating the 2026 San Diego market requires a precise understanding of how housing allowances interact with local property values. Using a combination of federal and state programs is the most effective way to secure a home and build lasting equity.
Ready to see how these programs apply to your specific rank and timeline? We invite you to a zero-pressure strategy session with David & Angela Cardenas and the Cardenas & Company Real Estate Group at cardenasandcompany.com or TrustSanDiego.com.
Information is for educational purposes and does not constitute legal or financial advice. David Cardenas, DRE 01862173.
Disclaimer
The information provided on this blog is for educational and informational purposes only and does not constitute legal, financial, or investment advice. While we strive for accuracy, real estate markets and insurance regulations (including Living Trusts and IUL strategies) are subject to change. David Cardenas (DRE 01862173) is a licensed real estate salesperson; however, this content does not create an agency relationship. Please consult with a qualified attorney or tax professional regarding your specific situation.