
Your best mortgage offer may not have the lowest advertised rate. If you’re learning how to prepare to buy a house in San Diego, start with a consistent loan scenario so you can compare lenders on equal terms, including loan type, fees, and estimated monthly payment.
It’s reasonable to focus on the rate, but the full housing payment matters just as much. Property taxes, homeowners insurance, and any HOA dues can change what fits your budget. A quote that looks attractive at first may not be the best match once you account for these expenses and the loan’s terms.
This guide offers a practical plan for preparing your finances, comparing Loan Estimates beyond the interest rate, and weighing tradeoffs among lenders. You’ll also learn how to coordinate your home search with financing guidance so your target price and monthly budget work together. Your lender can explain the loan options, while you decide what fits your plans and budget.
Key Takeaways
- Learn how to prepare to buy a house in San Diego by organizing your budget and financial documents before requesting lender quotes.
- Know which parts of your credit profile, down payment, loan type, and property details to discuss with each lender.
- Compare offers using the same loan scenario, then review the rate, APR, points, fees, cash to close, and monthly payment separately.
- Use a practical preparation checklist and talk with your lender before making major financial changes during the home search.
- Coordinate your search priorities with your financing plan, keeping loan decisions with your lender and homebuying guidance with your representative.
Table of Contents
How can you prepare for a mortgage-rate search in San Diego?
A competitive mortgage rate is only one part of a suitable loan offer. Compare it with fees and loan terms, because the headline rate alone won’t show the full cost of borrowing or whether the payment fits your budget.
Your mortgage rate is the percentage your lender charges to borrow money for a home purchase. It affects the interest portion of your payment, while your total borrowing cost also reflects items such as lender fees, discount points, and the loan’s length and terms. If you’re new to the process, this mortgage loan overview offers a general introduction to key terms.
To learn how to prepare to buy a house in San Diego, follow a clear sequence: set a sustainable monthly housing budget, organize your financial information, discuss your scenario with lenders, request offers based on the same assumptions, and ask how a rate lock works. A rate lock holds a quoted rate for an agreed period, subject to the lender’s terms. Ask when it expires and what happens if your closing date changes.
What should you organize before contacting lenders?
Gather an accurate picture of your income, employment, assets, debts, and credit history. Rather than guessing which paperwork a lender will need, ask for its document list and confirm how it will review your application.
Set a monthly housing limit before choosing a purchase range. Include more than principal and interest: property taxes, homeowners insurance, and any HOA dues can affect what you can comfortably afford. Your lender can explain financing, while your own budget helps you decide what payment works for your household.
How does a San Diego home search affect your financing plan?
Your target area and property type shape the questions to ask. When comparing a detached home with a condominium, for example, include estimated property taxes, insurance, and any HOA dues in your affordability conversation with the lender. For local context on neighborhoods and the purchase process, read the San Diego homebuying guide.
Cardenas & Company Real Estate Group helps buyers across San Diego and the South Bay, including San Diego, Chula Vista, Bonita, Del Mar, La Jolla, Otay Ranch, Carlsbad, Coronado, El Cajon, Santee, La Mesa, Lemon Grove, Encinitas, Imperial Beach, Oceanside, Poway, San Marcos, and Escondido. A real estate representative can help align your search with your stated budget and priorities, but does not set or provide mortgage rates. Your lender handles financing and explains available loan terms. If you’re relocating or connected to the military, include your move and decision timeline in the planning. The San Diego military relocation guide covers local considerations.
Which factors can affect the mortgage rate you are offered?
Your lender evaluates your full application and loan scenario, not one isolated number. Your credit profile, down payment, loan type, property details, and the lender’s pricing can all shape the quote. Ask what assumptions went into each offer before comparing them.
Published rates change, and an advertised rate may not match the terms available for your application. Confirm current pricing directly with each lender and request a written quote based on the same purchase details. As you learn how to prepare to buy a house in San Diego, treat each quote as a snapshot of a specific loan scenario, not a promise that applies to every buyer.
How can your credit profile and down payment influence an offer?
Your lender may consider your credit history and current obligations alongside the amount you plan to put down. These details can affect how the lender evaluates your application, but you shouldn’t assume that a particular score or down payment guarantees a specific rate.
Ask each lender which borrower details and loan assumptions shaped its quote. To make a useful comparison, keep the down payment and other scenario details consistent. That helps you see whether a difference comes from the lender’s pricing or from different assumptions.
Why do loan type and property details matter?
Conventional and VA financing are options to discuss with qualified lenders, not interchangeable quotes. Your intended occupancy, property type, and loan structure may affect eligibility or the terms a lender offers. If you’re military-connected, ask lenders directly about current VA requirements for your circumstances.
Ask how the lender handles discount points, too. Points are upfront charges that may lower a loan’s interest rate. Compare the added cost with the expected monthly savings to estimate the break-even period, the time it takes for those savings to equal what you paid. If you may sell or refinance before that point, paying upfront could cost more than it saves.
How should you interpret a rate quote?
Check the quote’s date, loan type, property assumptions, and any points or lender charges. Ask whether the quoted rate depends on conditions that still need review and confirm how long the quote remains available. A rate that looks favorable under one set of assumptions may not apply to a different property or loan structure.
Your lender sets and explains mortgage pricing. Your real estate representative can help connect your home search with your priorities without choosing or providing your loan. To discuss local homebuying priorities, explore local buyer representation.
How do you compare San Diego mortgage offers fairly?
Request written offers based on the same loan amount, down payment, property type, and rate-lock period. If one lender quotes a different scenario, you’re comparing different loans, not just different pricing.
Use a worksheet to keep each figure in its place. Ask lenders to explain their estimates and assumptions, especially when a fee or payment differs. This gives you a clearer basis for choosing than an advertised rate alone.
| What to compare |
Lender A |
Lender B |
| Loan amount, down payment, property type, lock period |
Enter quote |
Enter quote |
| Interest rate |
Enter quote |
Enter quote |
| APR |
Enter quote |
Enter quote |
| Discount points and lender fees |
List each charge |
List each charge |
| Estimated cash to close |
Enter estimate |
Enter estimate |
| Estimated monthly payment |
Enter estimate |
Enter estimate |
What should you look for beyond the interest rate?
The interest rate is the rate charged on the borrowed balance. APR, or annual percentage rate, is a broader measure that reflects the interest rate plus certain loan charges, expressed as a yearly rate. It can help you compare borrowing costs, but it doesn’t replace reviewing the actual loan terms, fees, and payment details.
A lower advertised rate doesn’t automatically mean a lower total cost if it comes with higher upfront charges or different loan terms. Ask each lender to identify discount points, lender fees, and the assumptions behind its estimate. Confirm that both offers use the same rate-lock period, and ask how long the quoted terms remain available and what could change them.
How can you compare points and rate-lock options?
Ask the lender to explain any points in writing, including the upfront charge and its effect on the payment and total cost. Consider how long you expect to keep the loan before deciding whether paying points fits your plans. A lower payment may matter less if the upfront cost takes too long to recover.
Have the lender explain the rate-lock timing, expiration date, and any extension conditions in writing. As you learn how to prepare to buy a house in San Diego, compare complete written terms rather than relying on a rate discussed in conversation. Clear assumptions make the tradeoffs easier to see.
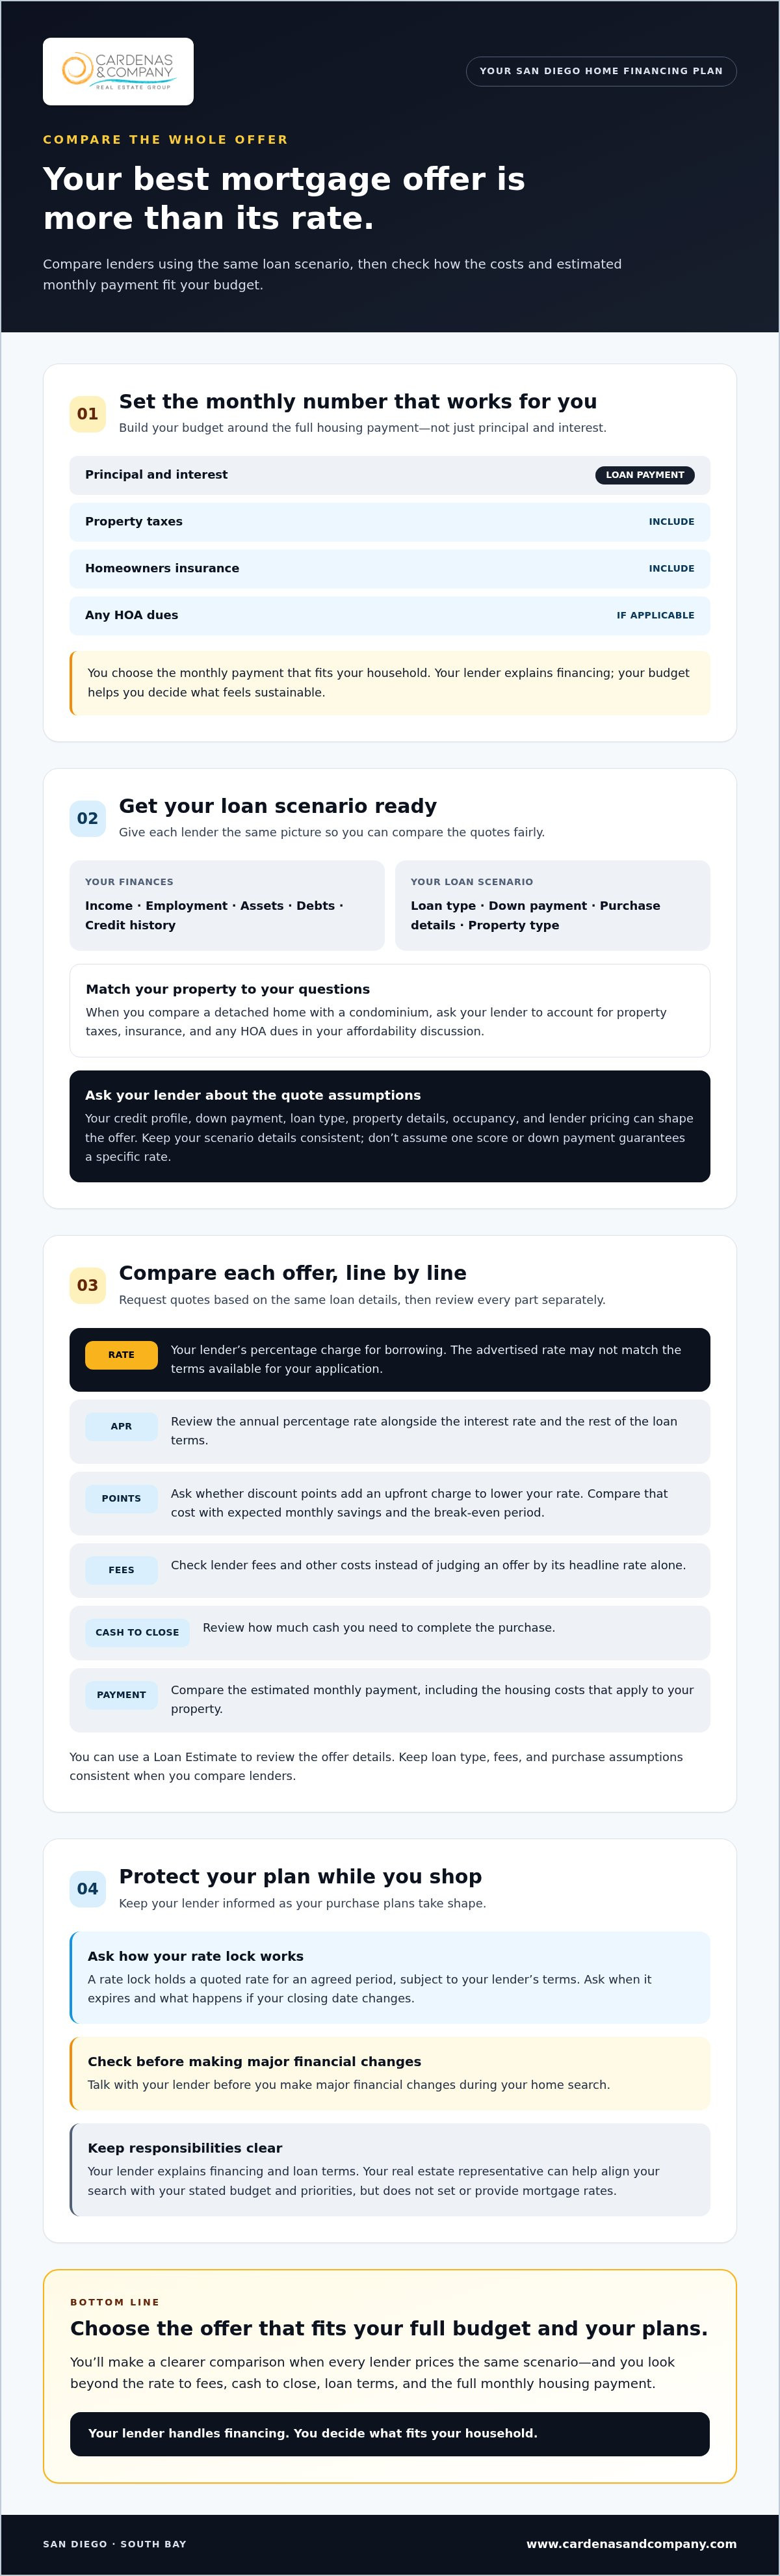
What steps can improve your mortgage preparation before making an offer?
A written plan helps you move from general research to a purchase decision without confusing a lender’s maximum loan amount with a comfortable monthly payment. If you’re learning how to prepare to buy a house in San Diego, keep your budget, lender estimates, and home search aligned from the start.
Use this checklist to organize the process:
- Set a monthly housing budget that includes estimated property taxes, homeowners insurance, and any HOA dues, not just principal and interest.
- Gather current information about your income, employment, assets, debts, and credit for lender review.
- Ask multiple lenders to evaluate the same documented purchase scenario, including the intended property type and down payment.
- Request written estimates and record the date, loan assumptions, rate, fees, estimated cash to close, and expiration details.
- Before making a major financial change, such as taking on new debt or changing employment, discuss the timing with your lender.
What is a sensible lender-comparison sequence?
Start with the payment you can sustain, then ask lenders to assess the same purchase scenario. Keep a record of each estimate’s date, assumptions, loan terms, charges, and how long the quoted terms remain available. If two estimates differ, ask the lenders to explain why instead of comparing figures built on different assumptions.
This process keeps your home search grounded in your priorities. A lender can explain financing options and estimates, but you decide what fits your monthly budget.
What should you ask before relying on pre-approval?
Pre-approval is an initial lender review based on information available at that point. It isn’t a guarantee of final loan approval. Ask what documents remain outstanding, which conditions could affect the review, how long the letter stays current, and when you may need to provide updated information.
Compare the pre-approved amount with your own budget. The figure a lender is willing to consider doesn’t set your household’s comfort level. Ask your lender to explain how the estimate relates to your planned payment and which assumptions it uses.
Your real estate representative can connect your home search with your stated priorities, while your lender handles financing questions and loan decisions. For a conversation about your local homebuying priorities, explore the team’s buyer representation.
Learn about San Diego buyer representation
How can you move from rate research to a confident San Diego purchase?
Choose a loan based on complete written terms and how they fit your plans, not the headline rate alone. Compare offers built on the same loan assumptions, then weigh the interest rate, APR, fees, estimated cash to close, monthly payment, and rate-lock terms together.
Your lender handles financing, evaluates your application, and confirms the terms available to you. Buyer representation has a different role: it helps connect your home search with your stated priorities, including location, property type, and budget. Cardenas & Company Real Estate Group supports buyers across San Diego and the South Bay and is affiliated with Realty ONE Group Pacific. The team does not provide mortgage rates or make loan decisions.
When should you revisit your financing comparison?
Check with your lender if your purchase scenario, loan assumptions, or timing changes. A different property, revised down payment, or change to your expected closing schedule can affect the lender’s estimate or the status of a rate lock.
Ask whether the lender needs updated documents or a new written estimate. Treat an earlier quote as a snapshot of the assumptions and timing it covered, not as a guaranteed rate or final loan approval. This distinction keeps your next steps grounded in current information.
Bottom Line: what is your next step?
As you decide how to prepare to buy a house in San Diego, keep your lender comparison consistent and in writing. Match loan assumptions, review fees and APR, and understand the rate-lock terms before choosing the offer that best fits your budget and plans.
You can work with your lender on financing while your real estate representative helps align the home search with your priorities. If you’d like to discuss what matters most in your San Diego or South Bay home search, you can connect with the team.
Explore San Diego homebuying support
Bottom Line: Choose a loan that fits your San Diego plans
As you decide how to prepare to buy a house in San Diego, compare complete written offers built on the same loan assumptions. Review fees, APR, payment, and rate-lock terms, then choose the option that fits your budget and plans.
Your lender handles financing and loan decisions. Cardenas & Company Real Estate Group, affiliated with Realty ONE Group Pacific, provides buyer representation across San Diego and the South Bay, including military relocation support for families moving to the region.
For help aligning your home search with your priorities, connect with Cardenas & Company Real Estate Group. The team supports buyers across San Diego and the South Bay.
Talk through your San Diego homebuying priorities with our team
What questions do San Diego homebuyers ask about mortgage rates?
How do I get the best mortgage rate in San Diego?
Compare written quotes from multiple lenders using the same loan amount, down payment, property type, and rate-lock period. Review the interest rate alongside APR, points, lender fees, estimated cash to close, and monthly payment. Your credit profile and loan details can affect an offer, so ask each lender which assumptions shaped its quote. This is a practical part of learning how to prepare to buy a house in San Diego.
Can I negotiate my mortgage rate with a lender?
Ask a lender whether it can improve its offer or adjust the costs attached to it. Bring a competing written quote based on the same loan scenario and ask the lender to explain differences in rate, points, and fees. The lender sets the terms it can offer, and a competing quote doesn’t guarantee a lower rate. Keep the comparison focused on the full loan cost.
Does getting pre-approved guarantee my mortgage rate?
No. Pre-approval is an initial review of your financial information and intended borrowing scenario, not a guaranteed final approval or rate. Your lender can explain what conditions remain, how long the pre-approval letter stays current, and whether your quoted rate is locked. If your income, debts, purchase details, or timeline change, ask whether the lender needs updated information or a new estimate before you rely on earlier terms.
What is the difference between a mortgage rate and APR?
Your mortgage rate is the percentage your lender charges on the amount you borrow. APR, or annual percentage rate, is a broader yearly measure that includes the interest rate and certain loan costs. Use APR as one comparison tool, not a substitute for reviewing the full terms. For a home in San Diego, also examine estimated cash to close and monthly payment so you understand both upfront and ongoing costs.
Should I pay discount points to get a lower mortgage rate?
Consider points only after your lender explains the upfront cost, payment change, and estimated break-even period in writing. Points are upfront charges that may lower your rate. The break-even period is how long it takes your monthly savings to equal that charge. Compare that timeline with how long you expect to keep the loan. If you may sell or refinance sooner, the upfront expense may not suit your plans.
How long can I lock a mortgage rate?
Your lender sets the available rate-lock period and explains its conditions, so confirm the details for your specific loan. Ask when the lock begins and expires, whether an extension is available, and what conditions or charges apply if your closing takes longer. A rate quote without a lock may change. Recheck the terms if your purchase scenario or timing shifts, especially before relying on an earlier estimate.
Can a real estate agent help me get a lower mortgage rate?
Your real estate agent doesn’t set mortgage rates or provide a loan. Your lender evaluates your application and offers financing terms. A buyer representative can help connect your home search with your budget and priorities, whether you’re comparing property types in Chula Vista, Bonita, or elsewhere in San Diego. Cardenas & Company Real Estate Group provides buyer representation across San Diego and the South Bay, including military relocation support.
Disclaimer
The information provided on this blog is for educational and informational purposes only and does not constitute legal, financial, or investment advice. While we strive for accuracy, real estate markets and insurance regulations (including Living Trusts and IUL strategies) are subject to change. David Cardenas (DRE 01862173) is a licensed real estate salesperson; however, this content does not create an agency relationship. Please consult with a qualified attorney or tax professional regarding your specific situation.