Showing up to a San Diego open house without a verified letter is like trying to buy a home with a handshake; it won't work in a market where properties attract an average of 3 offers within 25 days. With the median home price reaching $950,000 in March 2026, learning how to get pre-approved for a mortgage San Diego is your most vital strategic move to secure your family's future. We understand that current 6.44% interest rates and the fear of credit rejection create significant anxiety, but we are here to provide the expert reliability you need to move forward with clarity.
You deserve the peace of mind that comes from knowing your actual buying power before you start touring neighborhoods in Chula Vista or coastal San Diego. This guide will help you distinguish between a simple pre-qualification and a formal pre-approval while highlighting specific 2026 programs like the SDHC down payment assistance. We will outline the exact pathway to securing your letter so you can stop feeling overwhelmed and start making confident, competitive offers that protect your long-term interests.
Key Takeaways
- Understand why a formal lender commitment is the only way to get San Diego sellers to take your offer seriously in a competitive market.
- Learn how to optimize your debt-to-income ratio and credit score to secure the most favorable interest rates available in 2026.
- Master the step-by-step process of how to get pre-approved for a mortgage San Diego by organizing your financial documents and selecting the right local partner.
- Discover the common financial mistakes, like major purchases or career shifts, that can accidentally derail your loan funding at the last minute.
- Gain the tactical edge needed to treat your financed offer like cash during negotiations with sellers in Chula Vista and beyond.
Why Mortgage Pre-Approval is Your Best Strategic Advantage in San Diego
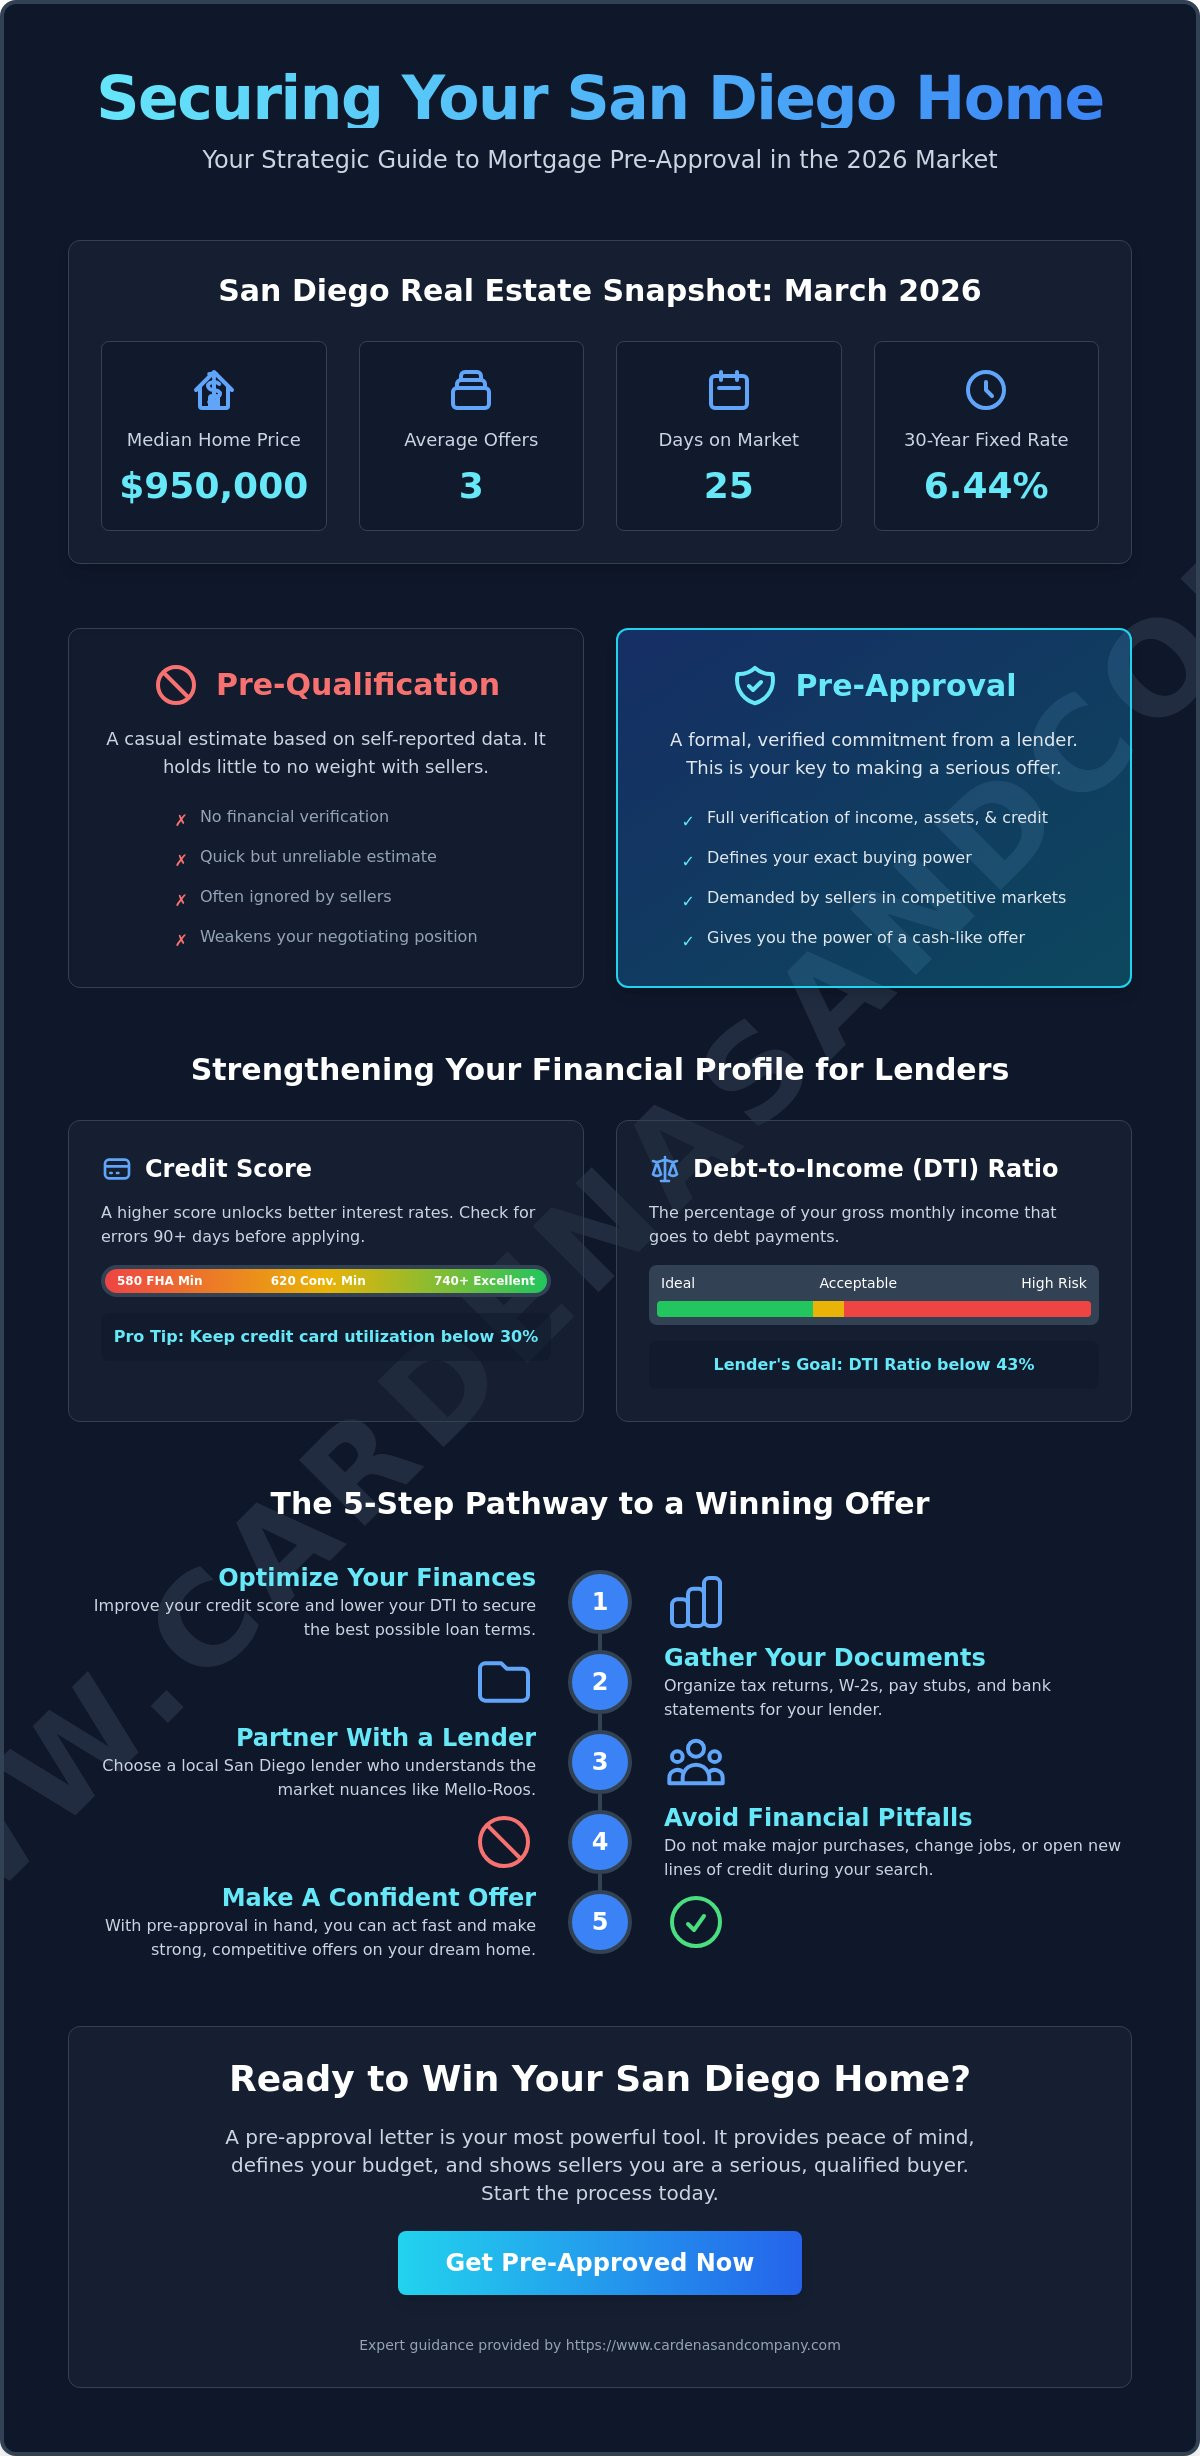
A mortgage pre-approval acts as a formal commitment from a lender to provide you with a specific loan amount. Unlike a casual estimate, this document is based on a rigorous verification of your income, assets, and credit history. When you understand what is a mortgage pre-approval? you realize it is the primary tool for establishing your credibility. In a city where the median home price hit $950,000 in March 2026, sellers will not even open your offer without this verified proof of funds.
Understanding how to get pre-approved for a mortgage San Diego helps you define your actual buying power. You avoid the heartbreak of falling in love with a home that sits outside your financial reach. This process provides a clear ceiling for your search. It ensures you remain within a budget that supports your long-term financial security and peace of mind. We view this as the first step in protecting your family's future legacy.
Pre-Qualification vs. Pre-Approval: Know the Difference
We often see buyers confuse these two terms, but the difference is massive. A pre-qualification is a simple estimate based on what you tell a lender; it carries zero weight in a negotiation. A pre-approval requires you to submit tax returns, W-2s, and bank statements for a thorough audit. In Chula Vista and surrounding areas, a pre-approval letter is the industry standard for any serious buyer. It shows the seller that a financial institution has already vetted your background and committed to the loan.
The 2026 San Diego Market Reality
The data from March 2026 shows that San Diego homes receive an average of 3 offers and sell in just 25 days. This speed leaves no room for delay. If you find a home that fits your vision for the future, you must act immediately. Having your letter ready allows us to submit an offer the same day a property hits the market. This proactive approach transforms you from a spectator into a serious contender.
Securing this letter also provides a sense of certainty in an environment where the 30-year fixed mortgage rate sits at 6.44%. Knowing your exact rate and monthly payment allows you to make decisions based on facts rather than anxiety. We believe that a well-prepared buyer is a confident buyer. By handling the technical details early, you can focus on the emotional journey of finding your next home with a sense of unwavering support.
Financial Preparation: Strengthening Your Profile for San Diego Lenders
Your financial profile is more than a collection of numbers; it is the pathway to your future home. When investigating how to get pre-approved for a mortgage San Diego, you must recognize that lenders evaluate your reliability through a specific lens. They aren't just looking at your bank balance. They are measuring your risk profile against the current 6.44% interest rate environment to ensure you can maintain long-term stability.
We often see buyers in Chula Vista surprised by how Mello-Roos taxes affect their borrowing power. These are special assessments used to fund local infrastructure like schools and parks in newer communities. Because lenders include these taxes in your monthly debt obligations, a high Mello-Roos payment can lower the total loan amount you are eligible to receive. This makes it vital to factor in the total effective tax rate, which typically ranges between 1.2% and 1.25% in San Diego County.
Your Debt-to-Income (DTI) ratio is another critical metric that lenders focus on during the audit. This is the percentage of your monthly gross income, which is your pay before taxes, that goes toward paying debts like student loans or credit cards. Lenders generally prefer a DTI below 43% to ensure you have enough breathing room for daily expenses. If you are unsure where your current profile stands, you can review our local resources to see how your finances align with current market requirements.
Optimizing Your Credit Score for Better Rates
Lenders look for a minimum credit score of 620 for conventional loans and 580 for FHA loans. To secure the most favorable terms, you should check your credit report for errors at least 90 days before applying. Keep your credit card utilization below 30% of your available limit to show financial discipline. You should also avoid opening any new lines of credit or making large purchases during this time, as these actions can cause your score to drop suddenly.
Calculating Your True San Diego Buying Power
Your true buying power must include the Verified Income from at least two years of stable employment. Underwriters will scrutinize your tax returns and W-2s to confirm your earnings are consistent. For middle-income households, programs like the San Diego Housing Commission (SDHC) offer $40,000 in down payment assistance for homes priced up to $1,250,000. Additionally, the California Dream for All program can provide up to 20% assistance, though it operates on a lottery system that requires early registration. Factor in monthly HOA fees if you are looking at condos in the South Bay, as these also count toward your DTI limits.
The 5-Step Process to Securing Your Pre-Approval Letter
Once you've audited your credit and calculated your budget, you're ready to move into the execution phase. Learning how to get pre-approved for a mortgage San Diego requires a methodical approach to ensure your application survives the scrutiny of an underwriter. We recommend starting with a local lender who understands regional nuances, such as the $1,104,000 FHA loan limit for San Diego County in 2026. A local expert ensures that your pre-approval letter carries weight with listing agents in neighborhoods like Eastlake or North Park.
The first step involves gathering your financial story through documentation. Next, you will select a lender and submit a formal application. This process triggers a hard credit inquiry, which is a necessary step for the lender to verify your creditworthiness. Fourth, the underwriter, who is the professional responsible for verifying your financial data, will review your file to issue the official letter. Finally, you must maintain your financial status quo until you close escrow. Escrow is the neutral third-party process that handles the exchange of money and documents during a home sale.
Maintaining the status quo is the most overlooked part of the process. If you change careers or finance a new vehicle after receiving your letter, you could reset your entire timeline. Lenders will perform a final credit check right before you sign your closing documents. Any major shift in your debt-to-income ratio can lead to a loan denial at the eleventh hour. We want to ensure your pathway to homeownership remains clear and predictable.
Essential Documentation Checklist
Lenders require a clear, paper-based trail of your financial history. You should organize these items into a digital folder for quick access. Having these ready allows you to respond immediately if an underwriter requests clarification during the review. Most San Diego lenders will require the following:
- Federal tax returns and W-2 statements from the past 2 years.
- Your most recent pay stubs covering at least 30 days.
- Full bank statements for the last 60 days, including all pages.
- Proof of secondary income, such as investment dividends or social security benefits.
- A signed gift letter if family members are assisting with your down payment.
Special Guidance for San Diego Military Families
Our military community has access to some of the most powerful home-buying tools available. As of April 27, 2026, the VA loan interest rate sits at 5.750%, offering a significant advantage over conventional rates. To start this process, you must obtain your Certificate of Eligibility (COE) from the Department of Veterans Affairs. We take great pride in supporting those who serve. For a deeper look at the specific benefits available to you, please see our Comprehensive Guide to Military Relocation in San Diego & Chula Vista (2026).
Avoiding Common Pre-Approval Pitfalls During the San Diego Home Search
Receiving your letter is a significant milestone, but it does not mean your loan is a certainty. A pre-approval is a conditional commitment based on your financial status at a specific moment in time. If your circumstances shift before you close escrow, the lender can and will revoke their offer. Understanding how to get pre-approved for a mortgage San Diego also means understanding how to protect that status until the keys are in your hand.
One of the most frequent mistakes we see involves large purchases on credit. Buying a new vehicle or financing a suite of appliances for your future home can immediately alter your debt-to-income ratio. Even if you can afford the monthly payment, the new debt might push you past the lender's strict limits. Similarly, moving large sums of money between bank accounts without a clear paper trail creates red flags for auditors. Keep your finances quiet and consistent during your search to avoid unnecessary stress.
Employment stability is equally vital. Lenders typically require a two-year history of steady income in the same field. If you decide to change careers or move from a salaried position to a 1099 contract role, you may reset your pre-approval timeline. Before making any professional shifts, consult with us to ensure your home-buying strategy remains intact. We are here to act as your proactive partners through every bureaucratic hurdle.
The "Waiting for Rates to Drop" Trap
Many buyers hesitate because the current 30-year fixed mortgage rate is 6.44%. However, trying to time the market often backfires in Southern California. With San Diego home prices expected to appreciate by 2% to 4% in 2026, waiting six months for a minor rate drop could result in paying $19,000 to $38,000 more for the same house. It is often more strategic to secure a home at today's price and refinance later if rates decrease. This approach prioritizes long-term wealth over short-term market fluctuations.
Protecting Your Pre-Approved Status
Stay in constant communication with your loan officer. Most lenders offer a 45-day rate lock, which protects your monthly payment from market volatility while you tour homes in Chula Vista. Remember that your file must pass Final Underwriting just days before closing. This is a secondary, deeper audit where the lender confirms nothing has changed since your initial application. By maintaining your financial status quo, you ensure that the pathway to your new life chapter remains open and secure.
Leveraging Your Pre-Approval to Win Your Dream Home in the South Bay
In the high-stakes environment of 2026, your pre-approval letter is more than a requirement; it is your strongest negotiating chip. When a seller in San Diego reviews multiple bids, they prioritize certainty over almost everything else. By showing that a lender has already audited your finances, you make your financed offer look as stable as a cash deal. This level of preparation allows us to advocate for you from a position of strength, often securing terms that would be unavailable to an unverified buyer.
Having your letter in hand also enables us to negotiate for faster closing times, which is a major incentive for sellers. While the average home sells in 25 days, a buyer who already understands how to get pre-approved for a mortgage San Diego can often shorten the escrow period. This efficiency can be the deciding factor when a seller is choosing between three similar offers. We want to ensure you are the most attractive candidate on the table so you can begin this new chapter with confidence.
We invite you to explore the current landscape of South Bay San Diego homes for sale to see what is available in today's market. With your financial foundation secured, you can tour these properties knowing exactly what you can afford. This clarity transforms the search from a source of anxiety into an exciting journey toward your family's future.
Crafting a Winning Offer Strategy
Christian Cardenas uses your pre-approval status to communicate your reliability directly to the listing agent. In competitive areas like Chula Vista, we often recommend presenting a "clean" offer with fewer contingencies. Contingencies are specific conditions that must be met, such as a home inspection or a formal appraisal, before the sale becomes final. Because your lender has already performed a deep dive into your profile, we can often tighten these timelines to make your bid stand out.
Building a Legacy Through Smart Homeownership
Securing a home in San Diego is the first step toward building long-term financial freedom and a lasting legacy. We view homeownership as a vital tool for asset protection and wealth generation for your family. To ensure your new investment is fully protected, we also recommend discussing living trusts in San Diego with a qualified professional. Protecting your home through a trust ensures that your hard-earned equity remains a secure resource for future generations.
Summary of Key Takeaways:
- A pre-approval letter is a formal lender commitment that makes your offer competitive against cash buyers.
- Financial preparation includes optimizing your credit score and managing your debt-to-income ratio.
- The 5-step process involves gathering W-2s, pay stubs, and bank statements for a thorough lender audit.
- Avoid major credit purchases or career changes during the search to protect your pre-approved status.
- Homeownership in San Diego is a long-term wealth strategy that should be protected with proper estate planning.
If you are ready to master the 2026 market and secure your future home, we are here to provide the expert guidance you deserve. Reach out to David & Angela Cardenas or The Cardenas and Company Real Estate Group for a zero-pressure consultation tailored to your unique story. You can also browse our current listings at any time by visiting https://www.cardenasandcompany.com/.
Secure Your Future in the San Diego Market
Mastering the technical details of how to get pre-approved for a mortgage San Diego provides you with a vital source of certainty in a market where the median home price reached $950,000 in March 2026. By organizing your documentation and auditing your financial profile early, you move from a place of anxiety to one of expert reliability. You now possess the strategic tools to protect your credit score and leverage your buying power to outshine competing offers in neighborhoods throughout Chula Vista and the greater San Diego area.
We view homeownership not merely as a procedural victory, but as the successful opening of a new life chapter for your family. Our team, led by local expert Christian Cardenas and affiliated with Realty ONE Group Pacific, is dedicated to providing the boutique-level attention required for your unique journey. We invite you to contact Cardenas & Company Real Estate Group for a zero-pressure consultation today. You can also browse our current listings to see the possibilities waiting for you. We look forward to being your stable anchor and helping you secure a future defined by long-term security and peace of mind.
Frequently Asked Questions
How long does a mortgage pre-approval last in San Diego?
A mortgage pre-approval letter is typically valid for 60 to 90 days. Lenders set this timeframe because your financial profile or market variables, such as the current 6.44% interest rate, can change over time. If your search for a home in Chula Vista extends beyond this window, your lender will simply need to refresh your file with your most recent pay stubs and bank statements to issue an updated letter.
Does getting pre-approved for a home loan hurt my credit score?
The process involves a hard credit inquiry, which typically lowers your credit score by 5 points or fewer. However, credit scoring models recognize that buyers need to shop for the best rates. As long as you perform your inquiries within a 14 to 45-day window, the bureaus generally treat them as a single event. This protects your credit health while you search for the best pathway to your future home.
Can I get pre-approved for a mortgage if I am self-employed?
You can certainly qualify for a loan if you are self-employed, though the documentation requirements are more extensive. Lenders will generally require two years of federal tax returns, 1099 forms, and a year-to-date profit and loss statement. Understanding how to get pre-approved for a mortgage San Diego as a business owner allows you to organize these documents early, ensuring a smoother audit by the underwriter.
What is the minimum credit score for a mortgage in San Diego in 2026?
For 2026, the minimum credit score is generally 620 for conventional loans and 580 for FHA loans. While these are the minimums, securing a higher score is beneficial because it dictates your final interest rate. With the median San Diego home price at $950,000, even a small reduction in your rate can lead to significant long-term savings and greater financial security for your family.
How much does it cost to get pre-approved for a mortgage?
Most lenders do not charge a fee for the pre-approval service itself. You may be responsible for a small credit report fee, which usually ranges between $30 and $50. We consider this a nominal cost for the peace of mind and the competitive advantage you gain when submitting offers in a fast-moving market like San Diego.
What happens if my pre-approval expires before I find a home?
If your letter expires, you don't need to start the entire process from scratch. Your lender will perform a quick update by reviewing your most recent financial documents, such as your last 30 days of pay stubs. This ensures your pre-approval remains accurate and reflects your current buying power. We recommend staying in close contact with your lender so your letter is always ready when the right property hits the market.
Can I change lenders after I have been pre-approved?
You are not committed to the lender that issues your initial pre-approval. You have the right to shop for different terms or better service even after you find a home. However, you should make this decision quickly once you enter escrow to avoid any delays in your closing timeline. We can help you compare local San Diego options to ensure you choose a partner that aligns with your long-term legacy goals.
Is a pre-approval required to attend open houses in San Diego?
You don't need a letter to attend most public open houses, but having one is highly recommended for serious buyers. In a market where homes receive an average of 3 offers, sellers and agents prioritize visitors who have already verified their finances. Knowing how to get pre-approved for a mortgage San Diego before you start touring ensures you can act immediately and with total confidence if you find your dream home.